Buying a home is a multi‑stage process: financial preparation, search, offer, financing, inspections, and closing. This guide walks first‑time and repeat buyers through each step with numbers, examples, and checklists so you can move methodically instead of guessing.
Overview
Step 1: Clarify What You Can Comfortably Afford
The 28/36 rule (and why it matters)
A common benchmark:
- Housing costs ≤ 28% of gross monthly income
- Total debt payments ≤ 36% of gross monthly income
Housing costs usually include:
- Principal and interest (mortgage payment)
- Property taxes
- Homeowners insurance
- HOA dues (if any)
Worked example: income-based budget
- Household gross income: $120,000/year
- Monthly gross income: $120,000 ÷ 12 = $10,000
- 28% housing limit: 0.28 × $10,000 = $2,800/month
So this household should generally target a total housing payment (PITI + HOA) at or below $2,800.
If they already have other debt:
- Car loan: $400/month
- Student loans: $300/month
Total non‑housing debt = $700.
36% total debt limit: 0.36 × $10,000 = $3,600/month
Maximum housing payment within 36% rule:
- $3,600 total debt – $700 existing debt = $2,900/month
The 28% rule says $2,800; the 36% rule allows $2,900. A cautious buyer will target ≤$2,800.
Step 2: Understand Down Payments and Cash Needed
Your down payment is only one portion of the cash required. You’ll also need closing costs and an emergency cushion.
Typical down payment ranges
- 3–5%: minimum for many conventional loans (with PMI)
- 10–15%: stronger offer, lower PMI
- 20%: avoids PMI and may secure better terms
Common closing costs
Usually 2–4% of the purchase price, including:
- Lender fees (origination, underwriting)
- Appraisal
- Title insurance
- Recording and transfer fees
- Prepaid taxes and insurance
Worked example: total cash to close
Target home price: $400,000
Option A – 5% down:
- Down payment: 5% × $400,000 = $20,000
- Closing costs (estimate 3%): 3% × $400,000 = $12,000
- Total cash to close ≈ $32,000
Option B – 20% down:
- Down payment: 20% × $400,000 = $80,000
- Closing costs (same 3%): $12,000
- Total cash to close ≈ $92,000
You should also hold 3–6 months of expenses in reserve after closing.
Step 3: Learn the Key Mortgage Terms
- Principal: The amount you borrow.
- Interest rate: Annual cost of borrowing, expressed as a percentage.
- APR (Annual Percentage Rate): Interest plus many fees, as a yearly rate; better for comparing loans.
- Term: Length of the loan (e.g., 15 or 30 years).
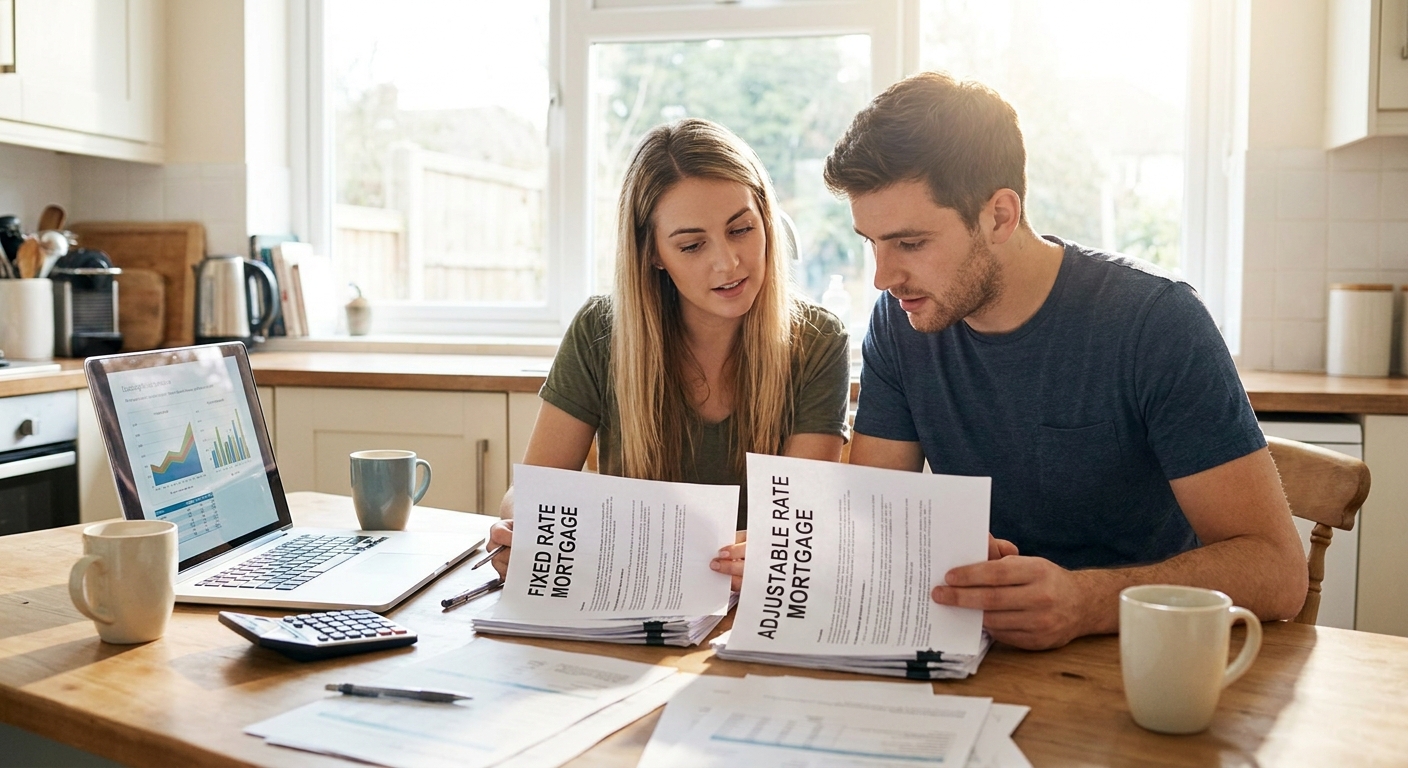
- Fixed‑rate mortgage: Rate stays the same for the entire term.
- Adjustable‑rate mortgage (ARM): Rate can change after an initial fixed period.
- PMI (Private Mortgage Insurance): Insurance added to your payment when you put less than 20% down on a conventional loan.
- Escrow: Account your lender uses to collect and pay taxes and insurance.
Step 4: Compare Monthly Payment Scenarios
Assume:
- Home price: $400,000
- 30‑year fixed, principal and interest only
Scenario 1: 5% down at 6.5% interest
- Down payment: $20,000
- Loan amount: $380,000
- Rate: 6.5%
Monthly principal & interest (P&I):
Using a standard mortgage formula or calculator, P&I ≈ $2,402/month.
Estimated taxes and insurance:
- Property taxes (1.25%/year): 1.25% × $400,000 = $5,000/year ≈ $417/month
- Insurance: ≈ $100/month
- PMI (approximate): $160/month
Total estimated payment:
- $2,402 + $417 + $100 + $160 = $3,079/month
Scenario 2: 20% down at 6.25% interest
- Down payment: $80,000
- Loan amount: $320,000
- Rate: 6.25%
P&I ≈ $1,971/month
Taxes and insurance (same estimates):
- Taxes: $417/month
- Insurance: $100/month
- PMI: $0 (20% down)
Total estimated payment:
- $1,971 + $417 + $100 = $2,488/month
Side‑by‑side comparison
| Item | 5% Down (6.5%) | 20% Down (6.25%) |
|---|---|---|
| Loan amount | $380,000 | $320,000 |
| P&I payment | $2,402 | $1,971 |
| Taxes + insurance (est.) | $517 | $517 |
| PMI | ~$160 | $0 |
| Total monthly | $3,079 | $2,488 |
| Cash to close (approx.) | $32,000 | $92,000 |
The 20%‑down buyer pays about $591 less per month, but needs an extra $60,000 in cash up front.
Step 5: Get Pre‑Approved (Not Just Pre‑Qualified)
- Pre‑qualification: Informal estimate based on self‑reported information. Useful for planning but weak in negotiations.
- Pre‑approval: Lender reviews documents (pay stubs, tax returns, credit). You receive a written letter stating a maximum loan amount.
What you’ll typically need:
- Last 2 years of W‑2s (or 1099s and returns if self‑employed)
- Last 30–60 days of pay stubs
- Last 2–3 months of bank statements
- ID and Social Security number
Step 6: Search with Clear Criteria
Create a written criteria list so you can evaluate homes consistently.
Location factors:
- Commute time and transit options
- School districts (even if you don’t have children)
- Noise, traffic, and future development plans
Property factors:
- Minimum bedrooms/bathrooms
- Type (condo, townhouse, single‑family)
- Age of major systems (roof, HVAC, plumbing, electrical)
- HOA dues and rules (if applicable)
Step 7: Make the Offer and Negotiate
Key terms in an offer:
- Purchase price
- Earnest money deposit
- Contingencies (financing, inspection, appraisal)
- Closing date
Earnest money: A good‑faith deposit (often 1–3% of price) held in escrow and applied to your down payment/closing at settlement.
Step 8: Inspections, Appraisal, and Final Approval
Inspections
Hire a licensed home inspector to evaluate:
- Structure and foundation
- Roof, attic, and insulation
- Plumbing and electrical
- Heating and cooling systems
If issues arise, you can often negotiate repairs or credits.
Appraisal
Your lender orders an appraisal to confirm the value supports the loan amount.
- If the home appraises at or above purchase price: proceed.
- If it appraises below price: you may renegotiate, bring extra cash, or exit (if you have an appraisal contingency).
Step 9: Closing Day
You’ll receive a Closing Disclosure at least three business days before closing. Review:
- Final loan amount and interest rate
- Monthly payment breakdown
- Closing costs and cash to close
On closing day you’ll:
- Sign the note, mortgage, and other legal documents
- Pay your cash to close (wire or cashier’s check)
- Receive keys once the deed is recorded
Checklist: Before You Start Touring Homes
- [ ] Calculate a conservative monthly housing budget
- [ ] Check your credit reports and correct errors
- [ ] Estimate down payment and closing cost savings
- [ ] Build an emergency fund (3–6 months of expenses)
- [ ] Get at least one formal pre‑approval
- [ ] Clarify your must‑haves vs. nice‑to‑haves
Common Mistakes to Avoid
Shopping by maximum approval, not comfort level
A lender’s maximum isn’t a lifestyle recommendation. Set your own ceiling.
Ignoring total housing cost
Taxes, insurance, HOA dues, and utilities can change affordability.
Draining all savings for the down payment
Keep reserve funds for repairs, job changes, and unexpected expenses.
Skipping the inspection in a competitive market
Even if you modify the contingency, understand what you’re buying.
Focusing only on the rate, not the APR and fees
A lower rate with high fees can be more expensive overall.
Not planning for maintenance
Budget 1–2% of home value per year for upkeep, especially for older homes.
Final Thoughts
Treat buying a home as a structured project: define your budget, understand the numbers, compare scenarios, and move step by step. A calm, data‑driven approach reduces stress and helps ensure your first (or next) home is sustainable for the long term.