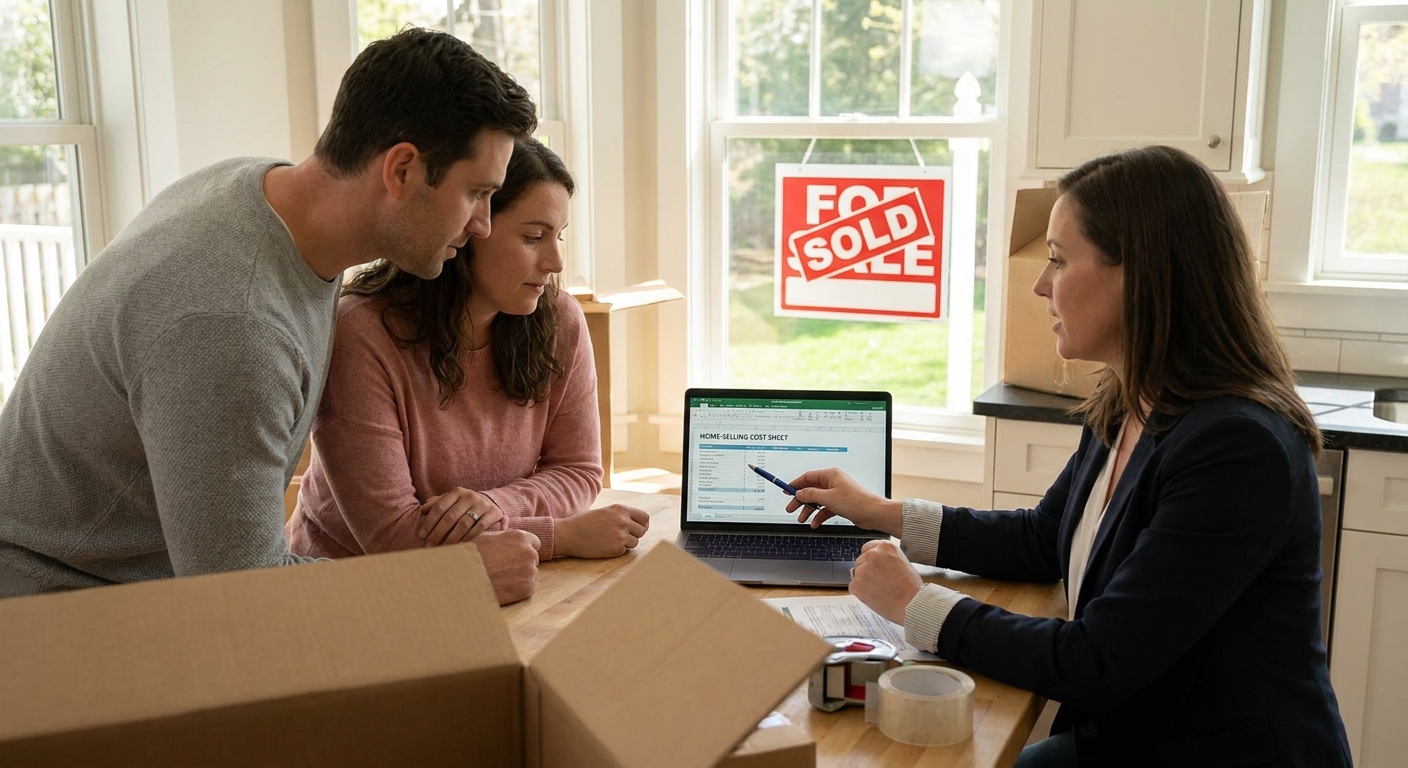
Most homeowners focus on the final sale price, but what really matters is net proceeds—the amount that actually reaches your bank account after paying off the mortgage and closing costs.
Why Your Net Proceeds Matter More Than Your Sale Price
This explainer breaks down each line item with realistic examples so you can predict your net within a close range before you list.
Step 1: Estimate Your Likely Sale Price
Use recent comparable sales and conservative assumptions.
Example Property
- 3-bed, 2-bath single-family home
- Location: Suburban area with stable demand
- Recent similar sales: $380,000, $395,000, $400,000
A reasonable working estimate might be $395,000.
Step 2: Estimate the Major Selling Costs
1. Real Estate Commissions
Though arrangements vary, a total commission of 5–6% of the sale price is common, split between the listing and buyer’s agents.
On $395,000:
- 5%: $19,750
- 5.5%: $21,725
- 6%: $23,700
For planning, use the midpoint: 5.5% ($21,725).
2. Seller Closing Costs
These can include:
- Title insurance (where customary for sellers)
- Transfer taxes or stamps
- Attorney or escrow fees
- Recording fees
Typical range: 0.5–1.5% of sale price.
On $395,000:
- At 1%: $3,950
3. Preparation and Repairs
This is highly variable. A conservative planning range is $1,500–$6,000 for non-structural items.
Example scope:
- Interior paint: $1,800
- Basic landscaping clean-up: $400
- Minor handyman repairs: $800
- Deep cleaning + carpet cleaning: $500
Total: $3,500.
4. Potential Buyer Concessions
Buyers may request:
- Seller credits toward closing costs
- Credits in lieu of repairs found during inspection
Common range: 0–2% of sale price.
For planning, assume 1%:
$395,000 × 1% = $3,950.
Step 3: Calculate Your Net Proceeds
Assume:
- Estimated sale price: $395,000
- Commission: 5.5% = $21,725
- Seller closing costs: 1% = $3,950
- Prep/repairs: $3,500
- Buyer concessions: $3,950
- Mortgage payoff: $295,000
Net Proceeds Calculation
$395,000
− $21,725 (commission)
− $3,950 (closing costs)
− $3,500 (prep/repairs)
− $3,950 (concessions)
− $295,000 (mortgage payoff)
= $66,875 estimated net.
This is the number to use when planning your next down payment.
Scenario Comparison: Different Sale Prices and Costs
Scenario A: Conservative Outcome
- Sale price: $385,000
- Commission (5.5%): $21,175
- Seller closing costs (1%): $3,850
- Prep/repairs: $2,500
- Buyer concessions (1.5%): $5,775
- Mortgage payoff: $295,000
Net = $385,000 − 21,175 − 3,850 − 2,500 − 5,775 − 295,000
= $56,700
Scenario B: Expected / Middle Outcome
- Sale price: $395,000
- Commission (5.5%): $21,725
- Seller closing costs (1%): $3,950
- Prep/repairs: $3,500
- Buyer concessions (1%): $3,950
- Mortgage payoff: $295,000
Net = $66,875 (as above)
Scenario C: Strong Outcome
- Sale price: $405,000
- Commission (5%): $20,250
- Seller closing costs (0.75%): $3,038
- Prep/repairs: $4,000
- Buyer concessions (0.5%): $2,025
- Mortgage payoff: $295,000
Net = $405,000 − 20,250 − 3,038 − 4,000 − 2,025 − 295,000
= $80,687
Now you have a realistic net range of about $56,000–$81,000.
How Your Net Affects Your Next Mortgage
Suppose you want to buy a new home for $475,000. Compare what happens with different net proceeds.
Case 1: Lower Net ($57,000)
- Down payment: $50,000 (keep $7,000 for moving and reserves)
- % down: 10.5%
- Loan: $425,000
- Rate: 6.75%, 30-year fixed
Approximate principal & interest: $2,756/month.
Case 2: Higher Net ($80,000)
- Down payment: $70,000
- % down: 14.7%
- Loan: $405,000
- Rate: 6.5%, 30-year fixed
Approximate principal & interest: $2,561/month.
Difference: about $195/month less in principal and interest, plus potentially better loan terms.
Key Terms Explained
- Net proceeds: The money you receive after paying off your mortgage and all selling costs.
- Seller credits/concessions: Amount the seller agrees to contribute toward the buyer’s costs.
- Title fees: Charges related to verifying and insuring property ownership.
- Transfer taxes: Taxes charged by a city, county, or state when property is sold.
- Payoff statement: Official document from your lender stating the exact amount needed to pay off your mortgage by a specific date.
Common Mistakes That Shrink Net Proceeds
Ignoring small inspection items
Buyers may demand a large credit for minor issues you could fix cheaply.
Underestimating repair costs
Not getting quotes before listing can lead to surprise concessions later.
Not clarifying what conveys with the home
Disputes over appliances or fixtures can delay closing and increase costs.
Neglecting tax implications
For many owner-occupants, gains may be partially or fully excluded, but verify with a tax professional.
Practical Net Proceeds Checklist
- [ ] Get a current mortgage payoff amount from your lender.
- [ ] Request an estimated seller net sheet from a title company, attorney, or agent.
- [ ] Budget for realistic prep and repair work.
- [ ] Run at least three net scenarios (conservative, expected, strong).
- [ ] Tie each scenario to your next purchase budget and down payment options.
By shifting your focus from headline sale price to carefully estimated net proceeds, you can plan your next housing move with far more precision and less stress.